


Consider two employees who each vest 100,000 dollars in restricted stock units in the same year. One sets nothing aside and faces a five-figure balance due at filing, along with an underpayment penalty. The other plans ahead, adjusts withholding, and times the sale past the one-year mark, owing little beyond what was already collected. The equity is identical. The outcomes are not.
The difference lies in understanding how RSUs are taxed at each stage, and in acting before the liability comes due rather than after.
This guide outlines how restricted stock units are taxed from grant through sale, explains why the standard 22 percent withholding falls short for many taxpayers, identifies the reporting error that can lead to double taxation, and reviews the planning strategies that help you retain more of your equity. All figures reflect 2026 U.S. federal tax rules.
What Are Restricted Stock Units (RSUs)?
A restricted stock unit is a company’s promise to give you shares of its stock on a future date, once you meet a condition. That condition is almost always staying employed for a set period, and sometimes hitting a performance target. Until the units vest, you own nothing you can sell. You hold a promise, not stock.
RSUs are the most common form of equity pay at public tech companies, where they often make up a large share of total compensation.
They are especially central for software engineers and other tech professionals. Because there is no actual stock in your hands at grant, there is nothing to tax yet. That single fact shapes everything that follows.
How RSUs Are Taxed at Every Stage
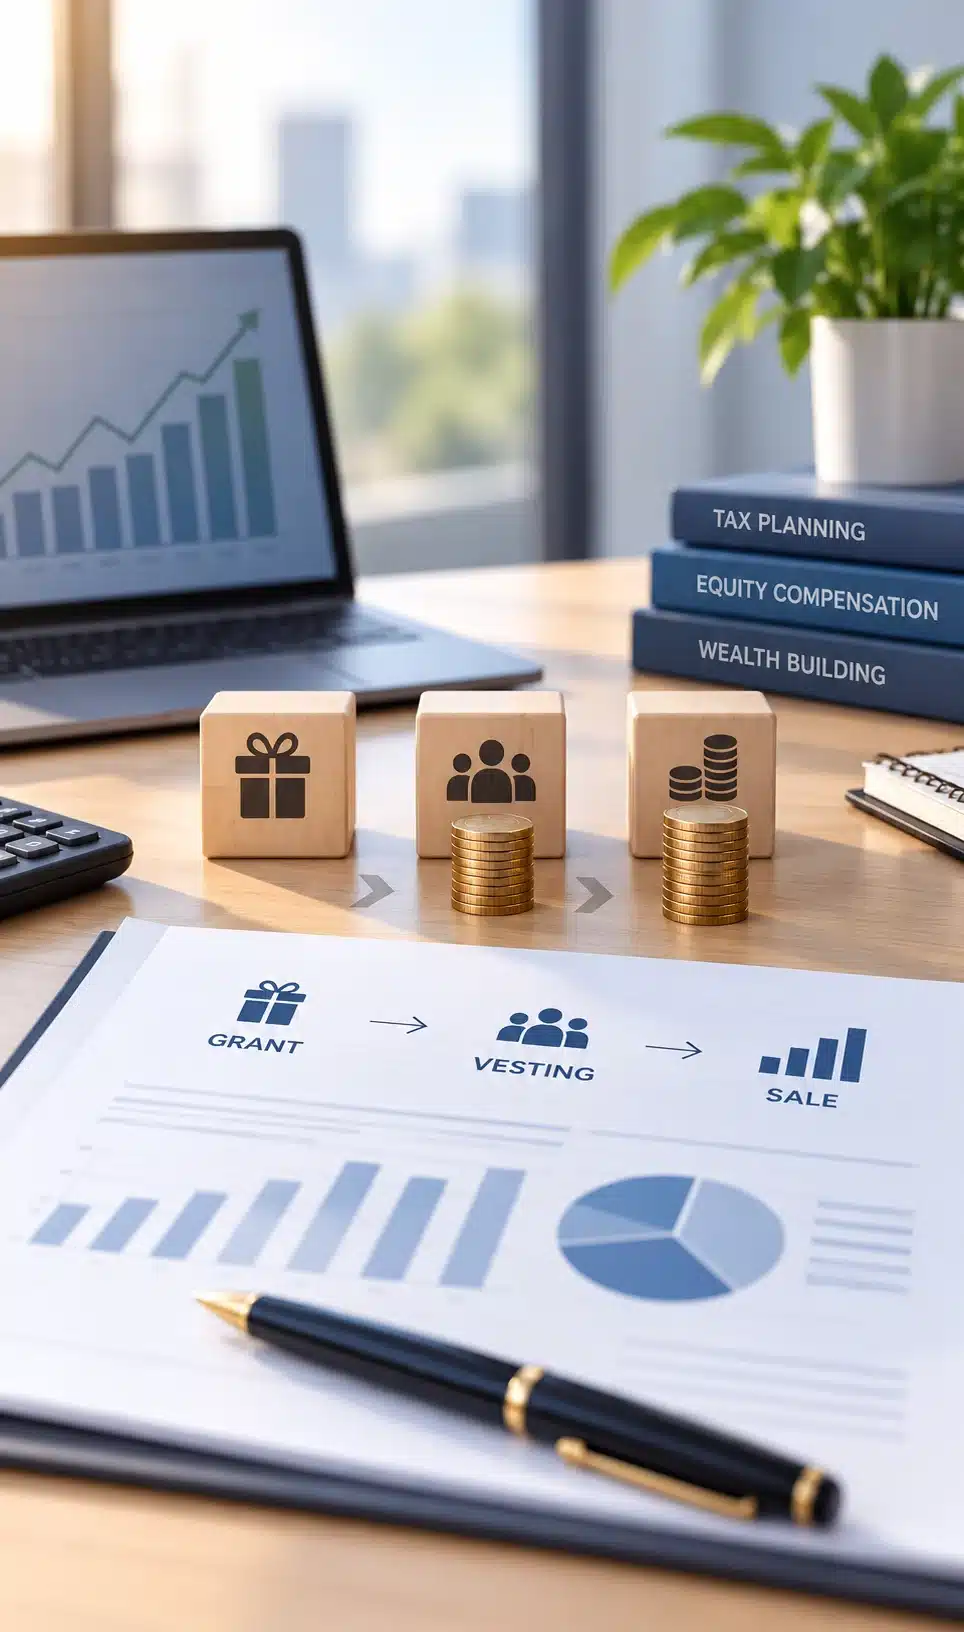
How are RSUs taxed? Every RSU tax question comes back to two taxable events, and keeping them separate is the key to understanding your bill. There is no tax at grant, ordinary income tax at vesting, and capital gains tax when you sell. In short, RSUs are taxed at your ordinary income rate when they vest and at capital gains rates when you later sell the shares.
| Stage | What happens | How it is taxed |
| Grant | You are awarded units on a vesting schedule | Not taxable |
| Vesting | Units convert into real shares you own | Ordinary income on the full value |
| Sale | You sell the shares | Capital gain or loss on the change in value |
Stage 1: Grant (No Tax)
At grant you owe nothing. A grant is only a promise of future shares, so there is no income to report. Your paperwork lists the number of units and the vesting schedule, such as 25 percent per year over four years, or quarterly vesting after a one-year cliff. Mark those vest dates. They are the days that actually matter for your taxes.
Stage 2: Vesting (Ordinary Income)
Vesting is the big taxable event, and yes, RSUs count as income at this stage. On each vest date, the fair market value of the shares that vested is treated as ordinary wage income. It lands in Box 1 of your W-2 and is taxed at your regular income tax rate, exactly as if you had received a cash bonus of the same size.
If 1,000 units vest when the stock trades at 50 dollars, that is 50,000 dollars of ordinary income for the year. It is subject to:
- Federal income tax at your marginal rate
- State income tax, if your state has one
- Social Security tax of 6.2 percent, up to the 2026 wage base of 184,500 dollars
- Medicare tax of 1.45 percent on all wages, plus an extra 0.9 percent above 200,000 dollars single or 250,000 dollars joint
The vest-date value also becomes your cost basis in the shares. Remember that number, because it is what keeps you from being taxed twice when you sell. Most companies handle the tax through sell to cover: they automatically sell enough of the newly vested shares to pay the withholding and deposit the rest into your brokerage account.
Stage 3: Sale (Capital Gain or Loss)
The tax implications of selling RSUs are simpler than the vesting stage: when you sell, only the gain counts. You are taxed on the difference between the sale price and your cost basis, which is the value already taxed at vesting. Because you already paid income tax on the vest-date value, that amount is never taxed again. How long you held the shares after vesting decides the rate:
- Held one year or less: short-term gain, taxed at your ordinary income rate.
- Held more than one year: long-term gain, taxed at the lower 0, 15, or 20 percent rates.
The holding clock starts on the vest date, not the grant date. Higher earners may also owe the 3.8 percent Net Investment Income Tax once modified adjusted gross income passes 200,000 dollars single or 250,000 dollars joint.
| Rate | Single filer | Married filing jointly |
| 0% | Up to 49,450 dollars | Up to 98,900 dollars |
| 15% | 49,451 to 545,500 dollars | 98,901 to 613,700 dollars |
| 20% | Above 545,500 dollars | Above 613,700 dollars |
The Withholding Gap: Why You Owe at Tax Time
The RSU federal tax withholding rate is a flat 22 percent, the IRS supplemental wage rate. For supplemental wages above 1 million dollars in a year, that RSU tax percentage rises to 37 percent on the excess. This RSU tax withholding rate is fixed. It does not know or care what tax bracket you are actually in.
For most people who receive RSUs, total income lands in the 24, 32, 35, or 37 percent federal bracket. Every RSU dollar is really taxed at that higher marginal rate, but only 22 percent was withheld. The difference is the withholding gap, and it shows up as a balance due, sometimes with an underpayment penalty on top.
A Real Example: What You Actually Pay
Here is how the two stages fit together for a single filer earning 180,000 dollars in salary, using illustrative numbers.
| Event | Calculation | Tax treatment |
| Vesting | 1,000 shares x 50 dollars = 50,000 dollars | Ordinary income at your marginal rate. Cost basis set to 50,000 dollars. |
| Withheld at vest | 22% of 50,000 = 11,000 dollars | If your marginal rate is 32%, the true tax is about 16,000 dollars, so roughly 5,000 dollars is still owed later. |
| Sale after 13 months | 70,000 proceeds minus 50,000 basis = 20,000 gain | Long-term gain taxed at 15% = 3,000 dollars. |
| If sold within 12 months | Same 20,000 gain | Short-term, taxed at 32% = 6,400 dollars. |
The lesson is in the last two rows. Holding one extra month cut the tax on the gain roughly in half, from 6,400 dollars to 3,000 dollars.
How Are RSUs Reported on Your Tax Return?
Because vesting income is baked into Box 1 of your W-2, there is nothing extra to enter for the vest itself. It flows onto your return as ordinary wages, the same as salary. Some employers also note the RSU amount in Box 14, which is informational only. The real reporting work happens when you sell.
When you sell vested shares, your broker sends Form 1099-B. You report each sale on Form 8949, carry the totals to Schedule D, and the net gain or loss lands on your Form 1040. Form 8949 is also exactly where you correct a cost basis the broker reported as zero, so you are not taxed a second time on income already sitting in your W-2.
| Form | What it covers | Where it goes |
| W-2, Box 1 | Vesting income, as ordinary wages | Already in your wages on Form 1040 |
| Form 1099-B | Proceeds from shares you sold | Reconciled on Form 8949 |
| Form 8949 | Each sale, with any cost-basis correction | Totals flow to Schedule D |
| Schedule D | Net capital gain or loss for the year | Carries to Form 1040 |
| Form 1040-ES | Estimated payments for the withholding gap | Credited on Form 1040 |
If you made estimated payments during the year to cover the withholding gap, claim them on your 1040 so you get full credit for what you already paid.
Common RSU Tax Mistakes to Avoid
The tax rules for RSUs are straightforward once you understand the two stages, but a handful of avoidable errors cost employees far more than the rules ever do. Three come up again and again at filing time, and each can be prevented well before you sell a single share. Knowing them in advance is often the difference between a clean return and an unexpected bill.
The Zero Cost-Basis Error
This is the error that quietly costs RSU holders the most money. Brokerages often report your cost basis as zero, or leave it blank, on Form 1099-B for sold RSU shares. If you accept that, you pay capital gains tax on the entire sale price, including the value you already paid income tax on at vesting. Your correct basis is the vest-date value that already appeared on your W-2. When the reported basis is wrong, correct it on Form 8949 and report the accurate gain.
Moving States Between Grant and Vesting
RSU income is state wages in most states, and the rules get tricky if you change states during the vesting period. Some states tax a portion of the income based on where you worked while the units vested, an issue of multi-state income allocation. High-tax states like California watch this closely.
Washington has its own RSU tax planning rules for equity gains. If you relocated while holding unvested RSUs, get advice before you file.
Ignoring the One-Year Holding Line
Selling shares a few days or weeks before the one-year mark turns a long-term gain into a short-term one, taxed at your full ordinary rate. When you plan to keep shares anyway, knowing that date can meaningfully lower the tax on the gain.
Strategies to Reduce Your RSU Taxes
You cannot change the fact that vesting is taxed as ordinary income, but you have real control over everything around it. Good RSU planning is rarely about avoiding tax altogether. It is about preventing surprises, shifting more of your gains into the lower long-term rates, and making sure you never pay more than you owe. Each of the moves below works best when applied before a vest or a sale rather than after, and most take only a short conversation with payroll or your advisor to put in place.
Close the Withholding Gap Early
Make estimated payments or increase withholding so you are not caught short in April, and so you avoid underpayment penalties. Reviewing this after each vest keeps small gaps from compounding into a large one.
Sell at Vesting to Diversify
Selling right at vesting locks in a basis equal to the value just taxed, so it triggers little or no additional gain. It is often the simplest way to diversify away from a heavy concentration in your employer’s stock.
Mind the Holding Period
If you plan to keep shares, crossing the one-year mark shifts the gain to the lower long-term rates. Coordinate large discretionary sales with the rest of your income for the year so a single sale does not push you into a higher bracket or trigger the extra Medicare and Net Investment Income taxes.
Coordinate With Other Equity
RSUs rarely sit alone. If you also hold incentive stock options, the timing of an exercise interacts with the alternative minimum tax, so the two are best planned together.
Mapping out a full stock option tax strategy before you exercise can prevent an avoidable bill. A Section 83(b) election, by the way, generally does not apply to RSUs, since it is meant for restricted stock you already hold.
Donate Appreciated Shares
Donating shares you have held more than a year can sidestep the capital gain while giving you a charitable deduction at fair market value, a clean option if you are already planning to donate appreciated stock.
How Capital Tax Can Help
RSUs look simple until vesting stacks on top of a strong salary and the numbers get real. A few coordinated moves before each vest date can save far more than they cost. Our team can help you:
- Right-size your withholding and estimated payments across every vest date so April holds no surprises.
- File RSU sales with the correct cost basis and catch broker reporting errors on Form 8949 before they cost you.
- Plan around state taxes and residency, which matters in non-conforming states like California.
- Coordinate your equity ahead of a liquidity event with pre-IPO planning.
- Build a multi-year plan for executives with concentrated equity.
- Handle the filing itself through individual tax preparation.
Bottom Line
RSUs are taxed twice over their life, once as ordinary income at vesting and once as a capital gain at sale, and the two are never the same dollars. The 22 percent default withholding under-covers most higher earners, and a wrong cost basis can tax you a second time on income you already paid. None of that is hard to manage once you see it coming. If you have RSUs vesting this year or expect a grant soon, schedule a meeting before your next vest date. A short review now can save a great deal at filing.
Frequently Asked Questions
Are RSUs taxed twice?
Not on the same dollars. The vest-date value is taxed once as ordinary income. When you sell, only the additional gain above that value is taxed. If it feels like double taxation, the usual culprit is a cost basis reported as zero on your 1099-B, which you can correct on Form 8949.
Why did I owe money on my RSUs even though taxes were withheld?
Your employer withheld federal tax at the flat 22 percent supplemental rate. If your marginal bracket is 24 percent or higher, that 22 percent under-withheld, and the shortfall is due at filing. This is the withholding gap.
How are RSUs taxed when they vest?
The fair market value of the vested shares is treated as ordinary wage income. It appears in Box 1 of your W-2 and is subject to federal and state income tax, Social Security, and Medicare.
Do RSUs count as income?
Yes. When RSUs vest, their fair market value counts as ordinary income and is reported in Box 1 of your W-2, the same as salary or a cash bonus. It is subject to income tax, Social Security, and Medicare.
Do I pay taxes on RSUs if I do not sell?
Yes. RSUs are taxed at vesting whether or not you sell the shares, because vesting itself is the income event. Selling later is a separate event that only taxes the gain since vesting.
What is my cost basis in RSU shares?
It is the fair market value of the shares on the vest date, the same amount already taxed as income. Verify it on your 1099-B, because brokerages sometimes report zero, and correct it on Form 8949 if needed.
Can I make an 83(b) election on RSUs?
In most cases no. A Section 83(b) election applies to restricted stock, not restricted stock units. RSUs are a promise of future shares, so there is generally nothing to elect on at grant unless the plan allows early delivery.